The Uranium Supply Gap Is Not One Number
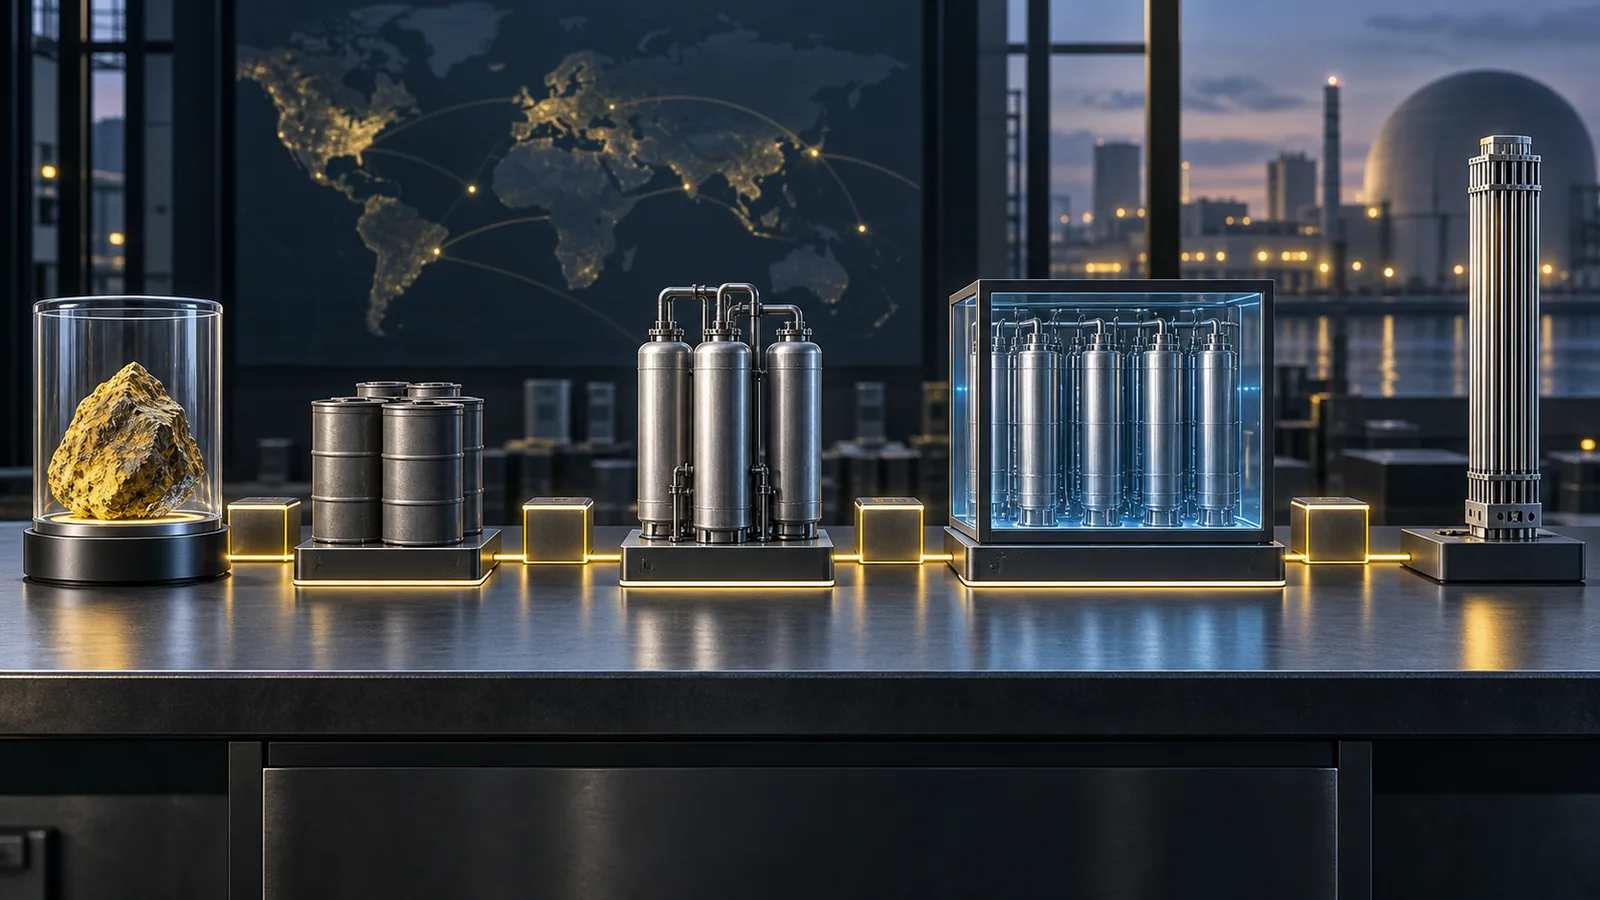
Image: MGNUM
Uranium may be the easiest commodity in the world to turn into a terrifying chart. Put mine production on one side, reactor requirements on the other, shade the gap red, and the investment thesis appears finished.
It is not. The chart may omit inventories, recycled material, underfeeding or overfeeding, conversion, enrichment, long-term contracts, project lead times, and the difference between resources in the ground and deliverable fuel.
Start by naming the material
“Uranium supply” can refer to several different things:
- uranium ore or concentrate from a mine;
- converted uranium ready for enrichment;
- enrichment work and enriched uranium product;
- fabricated fuel assemblies;
- inventories or other secondary sources.
A reactor does not run on a mine announcement. Each stage has its own capacity, contracts, geography, and bottlenecks. A constraint in conversion or enrichment can coexist with adequate geological resources. The reverse can also happen.
Why the official datasets need care
The IAEA and OECD Nuclear Energy Agency’s recurring “Red Book” program exists because uranium analysis requires resources, production, and demand to be studied together. The IAEA describes the work as a long-running effort to compile worldwide resource estimates and evaluate the global supply-demand balance.
There is also an easy-to-miss U.S. data wrinkle. Uranium appears on the final 2025 U.S. critical-minerals list, but the USGS 2026 Mineral Commodity Summaries explicitly notes that USGS does not collect uranium data and therefore does not provide a normal uranium chapter. A list entry is not a complete supply model.
Five questions for every shortage chart
- Which year? A 2035 requirement is not a 2026 delivery problem.
- Which unit and stage? Pounds of U3O8, tonnes of uranium, conversion capacity, and enrichment work are not interchangeable.
- Is demand observed or modeled? Reactor plans can slip; operating lives can extend.
- What counts as supply? Mine output alone or mine output plus inventories and secondary material?
- What price unlocks projects? A resource is not production until economics, financing, permission, and construction align.
The bullish case that survives scrutiny
A serious uranium thesis can still be bullish. Reactor construction, life extensions, fuel-security policy, and contracting cycles may create durable demand. Supply responses can be slow. Geographic concentration can raise strategic risk.
But the best version names the bottleneck. Is it permitted mine capacity, conversion, enrichment, transport, financing, or contracting? “There is a gap” is less useful than “this stage lacks qualified capacity during this period under these assumptions.”
That wording is less viral. It is also investable research rather than theatre.
Sources and limits
Resource and demand estimates change with price, policy, technology, and project schedules. Use the most recent tables available for a numerical model and disclose their date. This article is educational and is not investment advice.
Key takeaway
The uranium story may be tight, but a single red gap is not enough. Name the fuel-cycle stage, period, units, inventories, and price assumptions before treating a chart as evidence.
uraniumnuclear fuelsupply gapIAEA